All Categories
Featured
Table of Contents
Home costs have actually come under pressure after a duration of strong growth, with current data from the Dubai Land Department showing a drop in mortgage transactions and cash sales. We think the threat of an enduring migrant outflow and a serious decline in the real estate sector is low.
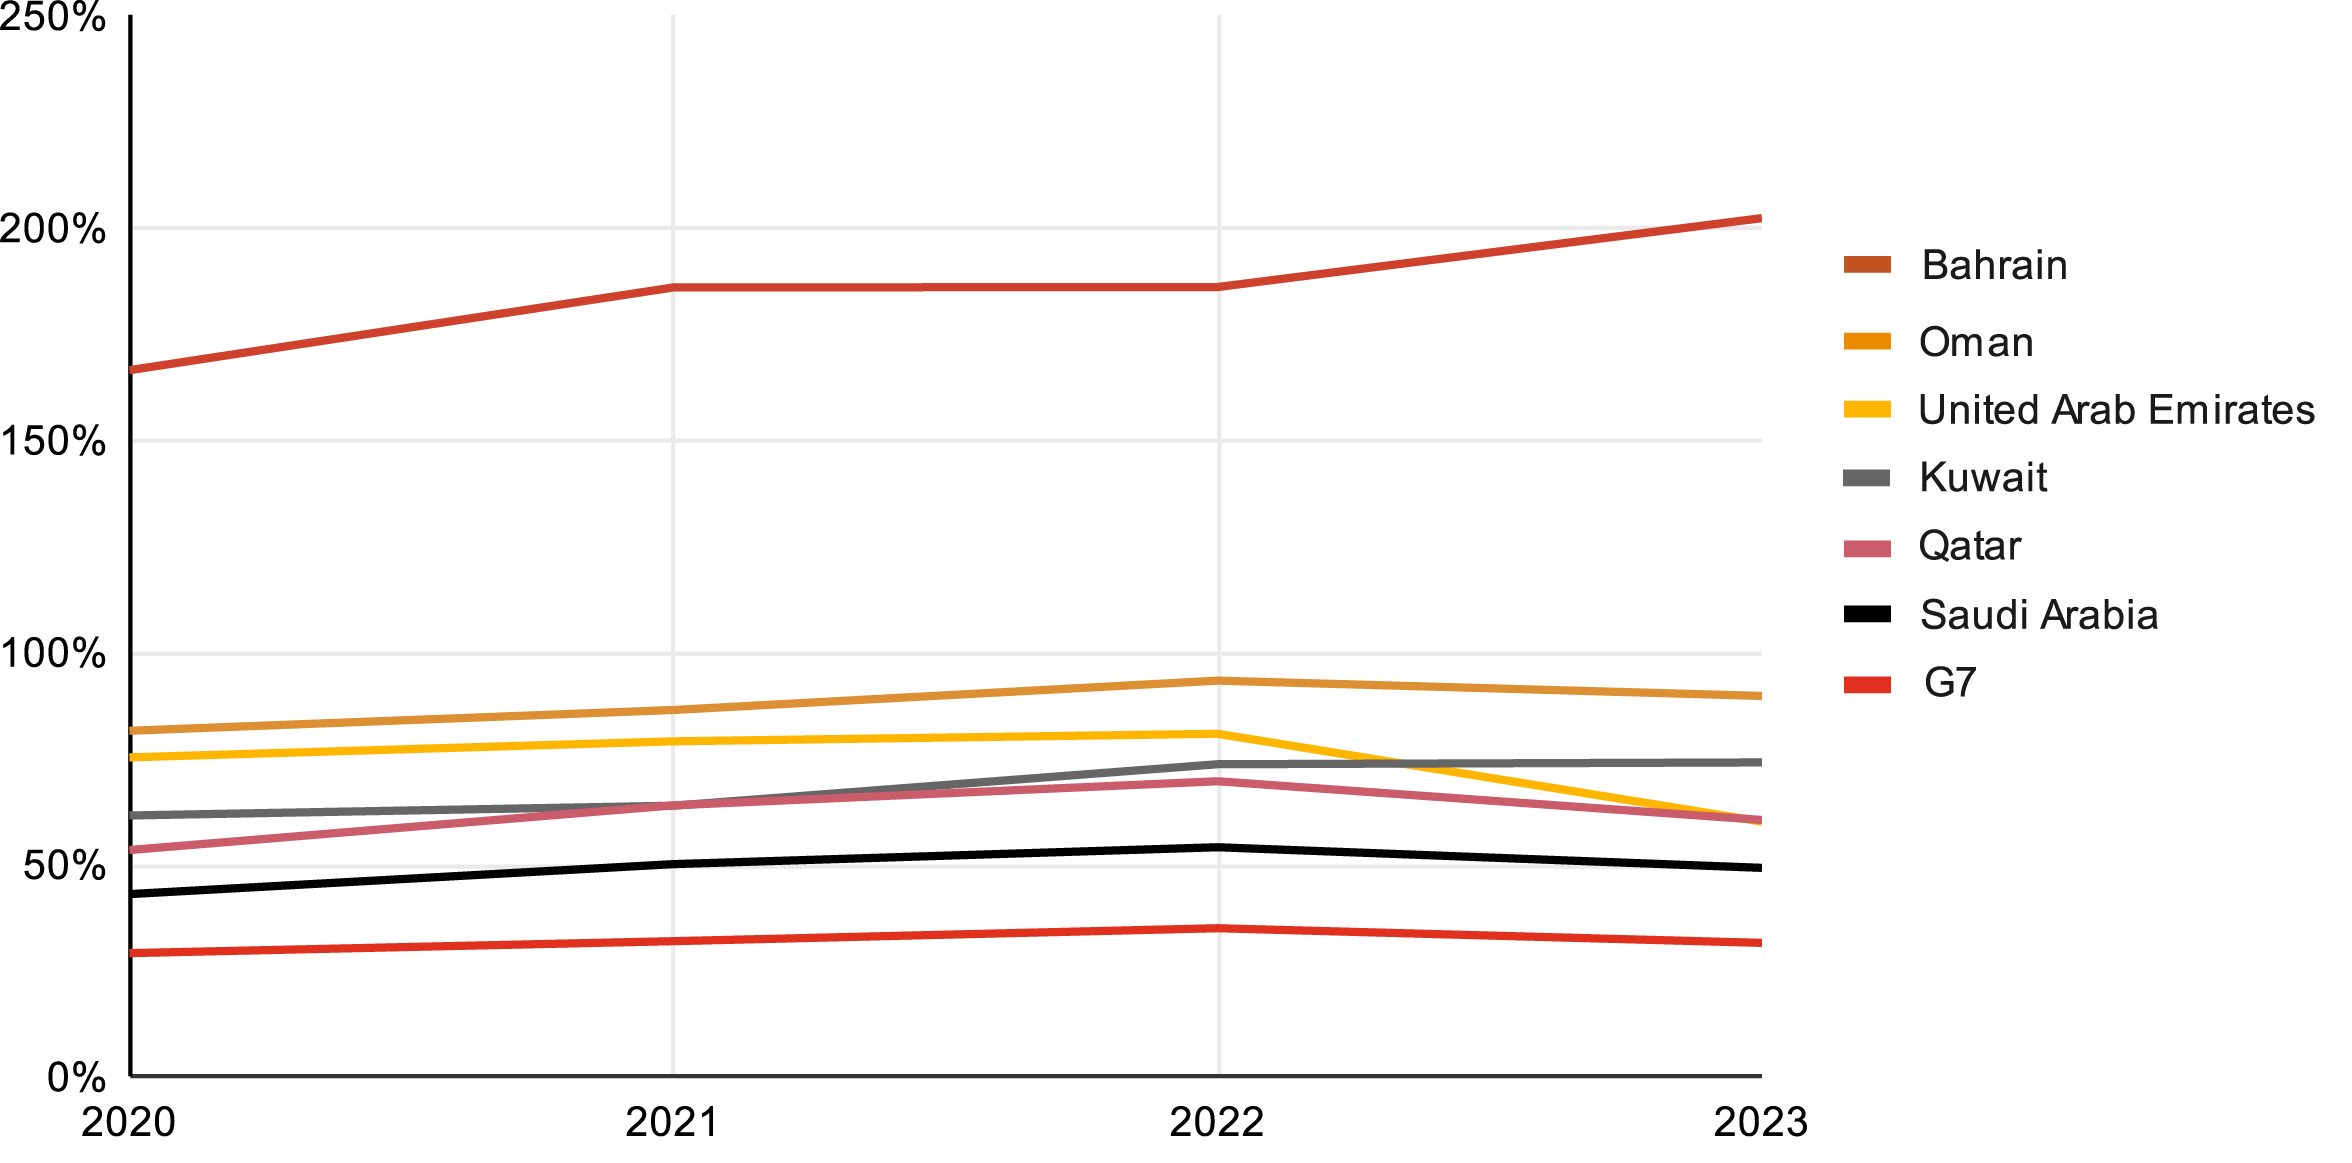
As an enduring US-Iran deal takes shape, the fallout from the conflict has actually tightened regional financial conditions, exposing vulnerabilities through capital outflows, larger bond spreads, and weaker investor belief. Many GCC sovereigns carry fairly little financial obligation and funding dangers are therefore limited in the UAE, the central bank's liquidity management has actually alleviated instant concerns.
That said, Bahrain has actually been able to depend on support from neighbours, consisting of Saudi Arabia and the UAE, and it successfully raised $1bn from an oversubscribed sovereign bond sale this month, marking the very first offering from the region considering that the war started. High-frequency financial data underscore the stress on regional public finances from the dispute.
The 2026 Investment Landscape in Arabia
In Saudi Arabia, the budget deficit more than doubled to SAR125.7 bn, or about 9% of GDP in Q1, driven by a decline in oil earnings and a surge in costs, especially on subsidies, showing contingency outlays connected to the regional environment and an acceleration of Vision 2030 costs. In Qatar, the crisis brought oil and gas income to a stop, swelling the deficit spending to the biggest considering that 2017.
GCC inflation characteristics stay irregular, with food prices the primary source of upward pressure and inflation in this category fortifying in Kuwait, Oman and Qatar. By contrast, food inflation remains fairly subdued in Saudi Arabia, likely reflecting the mitigating effect of its bigger domestic food production base and greater supply-chain resilience.
We continue to see cost pressures as mostly temporal rather than a sign of a sustained inflationary cycle. Accordingly, we anticipate typical inflation to reduce to 2.1% y/y in 2027 as temporary supply-side pressures dissipate. With near-term inflation raised and transit through the Strait most likely set to resume slowly, we expect the US Federal Reserve to keep interest rates on hold till December, and local rate policies to do the same.
We expect Iran's GDP to shrink by 10.8% this year (we anticipate a 9.4% contraction three months ago). Oil production and exports, which offer essential profits and FX inflows, have been reduced by the US naval blockade, while non-oil activity has actually been significantly hit. In Iraq, oil exports have collapsed to a trickle and we're forecasting GDP to agreement by around 22% this year, with a sharp 33% rebound in 2027 as oil exports normalise.
By contrast, Syria continues to reintegrate into the international economy after more than a decade of civil war. We prepare for GDP growth to average 9.6% over 2026-2027, supported by renewed financial investment, especially in banking and energy, monetary reforms, and the gradual reopening of local trade links.
Global Investment Opportunities across the GCC
The World Bank has actually slashed its 2026 development forecast for Middle East economies, stating total GDP development in the area is expected to slow from an approximated 3.6% in January to 1.8% for 2026. The closure of the tactical Strait of Hormuz, and destruction of energy and public facilities, had interfered with markets, increased financial volatility, and deteriorated the 2026 growth outlook, the World Bank Group said in its Economic Update for the Middle East, North Africa, Afghanistan and Pakistan.
Beyond Net-Zero: The Social Impact of Gulf ESG InitiativesThe April 2026 World Bank's Macro Hardship Outlook anticipates that the region's aggregate (excluding the Iran) GDP development will slow down to 1.8 percent in 2026, below 4.0 percent estimated for 2025. The 2026 forecast has actually been reduced by 2.4 portion points because the January projections, reflecting the adverse effects of the ongoing dispute.
Saudi Arabia: Forecast was reduced by 1.2 portion points because January. Development is now anticipated to slow from 4.3% in 2025 to 3.1% in 2026, noting that Saudi Arabia's outlook remains the strongest amongst Gulf economies. United Arab Emirates: Growth forecast for the UAE has fallen by 2.7 percentage points because January.
Qatar: Notably, growth projection for the Qatari economy has actually seen a sharp decrease of 11.0 percentage points since January. The economy is now anticipated to record a contraction of 5.7%, below an approximated development of 5.3%, due to extreme blockage to melted gas supplies. Qatar is a crucial gamer in the worldwide energy market, with a global market share of melted gas (LNG) materials ranging in between 20% and 21%.
Kuwait relies completely (100%) on the Strait of Hormuz to export its unrefined oil and derivatives. Consequently, closing the strait would imply a total shutdown of the country's monetary lifeline, instantly halting revenue inflows to the state spending plan. Bahrain: Growth forecast for Bahrain's economy has decreased by 1.8 portion points since January.

Latest Posts
Why International Investment Flows Surge in 2026?
Why Foreign Capital Inflows Change in 2026?
Key Stock Market Trends Across the GCC